IR35 Status Determinations: What Contractors Can Learn from the FCDO Review
A significant change in the way the Foreign, Commonwealth & Development Office (FCDO) classifies contractors provides a timely reminder of why IR35 status should never be treated as a simple box-ticking exercise.
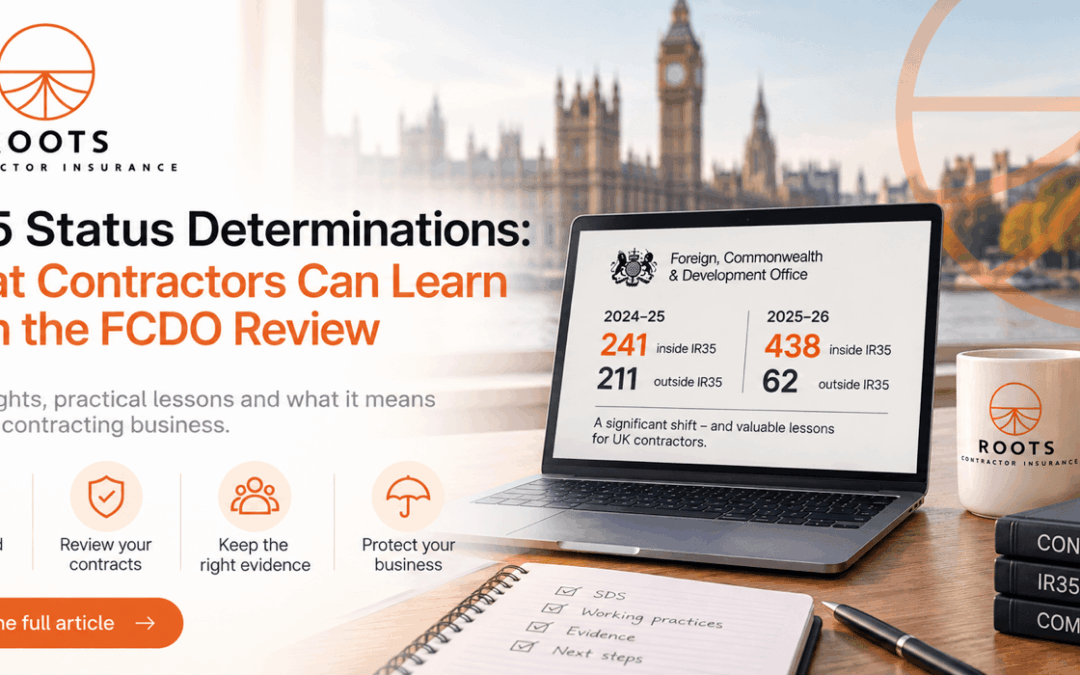
Figures reported from the department’s latest accounts show that, in 2024–25, 241 engagements were determined inside IR35 and 211 outside. In 2025–26, that changed dramatically: 438 of 500 engagements were determined inside IR35, with just 62 outside. The FCDO has previously acknowledged that a review moved a high number of engagements previously assessed as outside IR35 to inside, while the associated HMRC review remains ongoing.
The individual circumstances behind those determinations are specific to the department. Nevertheless, there are useful lessons for contractors and the organisations engaging them.
A Status Determination Isn’t Just a Label
For medium and large private-sector organisations and public authorities, the off-payroll rules generally place responsibility for determining employment status on the client.
Where the rules apply, contractors should normally receive a Status Determination Statement (SDS) explaining whether the engagement is considered inside or outside IR35 and the reasons for that conclusion.
The FCDO figures demonstrate just how significantly an organisation’s view of its contractor population can change.
That doesn’t mean that a higher proportion of inside-IR35 determinations is necessarily correct or incorrect. It does demonstrate why each engagement should be considered on its individual facts rather than contractors assuming that a particular client, role or profession is automatically inside or outside IR35.
Contracts and Reality Need to Agree
IR35 status is not determined by the title at the top of a contract.
The contractual agreement is important, but so are the actual working practices.
Questions can include the degree of control exercised by the client, whether there is genuine scope for substitution, the obligations between the parties, financial risk and whether the contractor is genuinely operating independently.
A contract could, for example, describe considerable autonomy while the reality involves the client closely controlling how services are performed.
Conversely, an engagement may genuinely operate on an independent, project-led basis.
For contractors, the important point is consistency: the contract should accurately describe the relationship that exists in practice.
Don’t Ignore an SDS You Disagree With
A contractor receiving an inside-IR35 determination shouldn’t assume there is nothing they can do.
The off-payroll regime provides a status disagreement process. Contractors can raise representations where they believe the determination is incorrect, and the client must consider the representations and respond within the statutory process.
That doesn’t guarantee the determination will change.
It does, however, make evidence particularly valuable.
Rather than simply stating ‘I am outside IR35’, a contractor should be capable of explaining why. That could involve specific contractual provisions and evidence demonstrating how the engagement actually operates.
An independent IR35 Contract Review can also help identify potentially problematic contractual terms and provide contractors with a clearer understanding of their position.
Evidence Matters Before a Dispute Starts
One of the strongest practical lessons for contractors is to maintain contemporaneous records.
Useful documentation can include the signed contract and schedules, an IR35 status assessment or contract review, correspondence concerning working arrangements and appropriate evidence demonstrating how services are delivered.
The aim shouldn’t be to manufacture an outside-IR35 case retrospectively.
Instead, contractors should preserve evidence of what genuinely happened.
That distinction becomes particularly important when an engagement has lasted for months or years and memories of day-to-day arrangements inevitably become less precise.
What Does ‘Reasonable Care’ Mean?
The FCDO situation also highlights the concept of reasonable care.
Clients responsible for determining status cannot simply issue arbitrary decisions. HMRC’s off-payroll framework requires reasonable care to be taken when reaching determinations.
For contractors, this is important because an SDS should represent a considered assessment rather than an automatic classification based purely on job title or profession.
Where the reasoning appears inconsistent with the actual engagement, contractors should consider raising the issue with the client.
Equally, contractors need to provide accurate information about their working arrangements. A robust status assessment depends upon both parties describing the relationship correctly.
Where IR35 Insurance Fits
Even where considerable care has been taken, employment status disputes can be complex.
IR35 Insurance provides protection against representation costs and liabilities associated with an HMRC IR35 investigation, subject to the policy’s terms, conditions and level of cover.
It should complement rather than replace good compliance.
A sensible approach combines properly drafted contracts, genuine working practices, appropriate evidence, periodic review and suitable protection against the remaining risk.
Contractors should also consider exposures unrelated to IR35. Professional Indemnity Insurance can protect against covered allegations concerning professional services, while Public Liability Insurance addresses third-party injury and property-damage risks. Employers’ Liability Insurance may also be relevant or legally required depending on the contractor company’s circumstances.
The Bigger Lesson for Contractors
The FCDO’s experience illustrates why employment status deserves ongoing attention.
An engagement shouldn’t be assumed to remain outside IR35 simply because it began that way, nor should a contractor automatically accept that an inside determination must be correct.
Working arrangements can change. Contracts can be renewed. Responsibilities can expand. Clients can reconsider their approach.
For contractors, the strongest position is therefore one that can be explained, evidenced and defended.
Frequently Asked Questions
What is an IR35 Status Determination Statement?
An SDS records the client’s conclusion about a contractor’s employment status for the off-payroll rules and gives the reasons behind that conclusion where the client is responsible for making the determination.
Can a contractor challenge an inside-IR35 determination?
Yes. Where the off-payroll rules apply, contractors can make representations through the status disagreement process if they believe an SDS is incorrect.
Can an IR35 position change during a contract?
Potentially. Material changes to contractual terms or actual working practices can affect the employment-status analysis, making periodic review sensible.
Does IR35 Insurance determine whether I am outside IR35?
No. Status needs to be assessed separately. IR35 Insurance is designed to provide specified protection if an HMRC investigation occurs, subject to the particular policy terms.